Debtless
The short answer
A bank loan payment calculator estimates a principal-and-interest payment from the loan principal, annual interest rate and term in months. When a fee is deducted from the advance, the principal you repay can exceed the cash you receive. Do not confuse that gross principal with the disclosure’s “amount financed,” which subtracts prepaid finance charges. The hypothetical example below uses a 12.44% interest rate excluding fees; it is not the loan’s fee-inclusive APR.
Mistake 1: confusing cash received with gross loan principal
Some personal loans deduct an origination fee from the advance. In that arrangement, distinguish the gross loan principal you repay from the cash you receive. The CFPB’s Regulation Z disclosure rules subtract prepaid finance charges when calculating “amount financed”; that disclosed figure is not automatically the principal input for a principal-and-interest calculator.
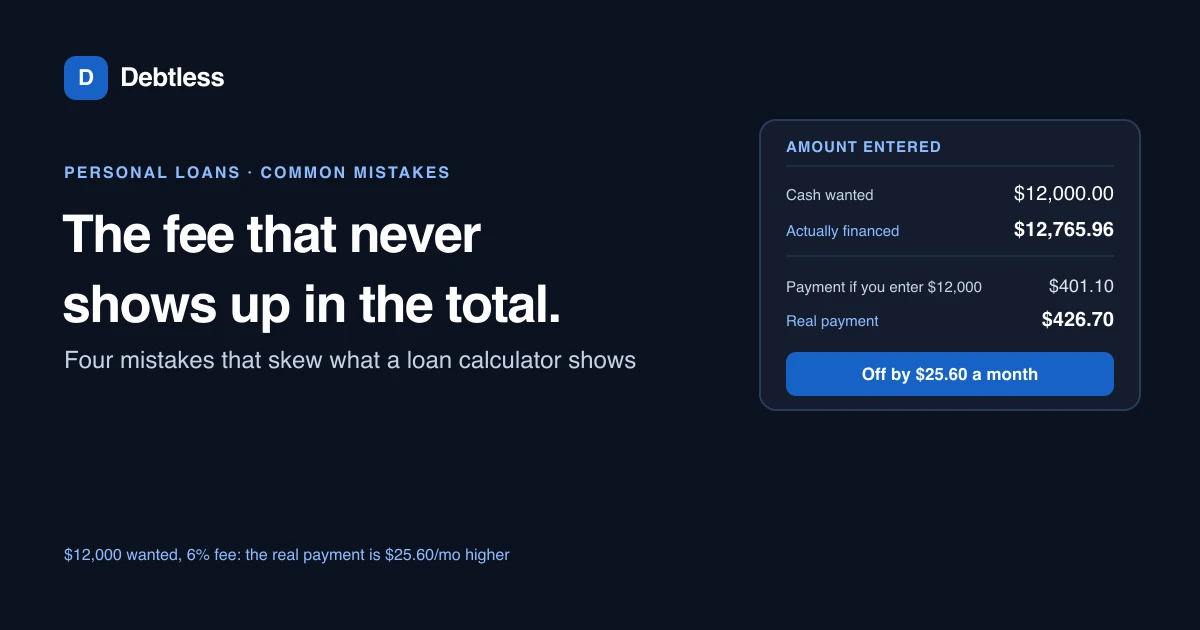
Suppose you need $12,000 in cash and a 6% origination fee is withheld from the gross principal. A $12,765.96 principal less the $765.96 fee leaves $12,000.00 after rounding. At a hypothetical 12.44% annual interest rate excluding fees over 36 months, that principal produces a $426.70 monthly payment. Entering $12,000 as the principal instead produces $401.10, a $25.60 monthly understatement. Check the principal, fee treatment and interest rate in the loan agreement; do not add a fee again if it is already included in the principal.
Mistake 2: treating the annual rate as a monthly one
Read whether the calculator expects an annual or monthly interest rate. If it expects an annual rate, enter that figure and let the calculator convert it internally; do not divide it by 12 first. Mixing annual and monthly rates can distort the payment estimate, so check the input label before comparing results.
On the same $12,000 loan at a 12.44% annual interest rate over 36 months, treating that 12.44% as a monthly rate rather than an annual one pushes the calculated payment to $1,515.05, nearly four times the real $401.10. A payment that far off from what you expected is usually the first sign something in the setup is wrong.
Mistake 3: entering the term in years where the calculator wants months
Loan applications and calculators don't agree on units. Some ask for the term in years, some in months, and typing "3" into a field built for months turns a 36-month loan into a 3-month one, with a payment large enough to be obviously wrong the moment it appears.
This is closer to a typo than a genuine misunderstanding, but it's common enough to check every time: read the label on the field, not just the number you already have in your head.
Mistake 4: assuming a quoted rate is locked in
According to the CFPB, a fixed APR stays the same for the life of the loan while a variable APR can change with a benchmark index, and the two produce very different long-run totals even when the starting rate looks similar. A calculator run once with a promotional or introductory rate won't reflect what you'll actually pay once that rate resets.
A similar principal-input mix-up shows up on a car loan; Car Payment Calculator: A Worked Example With Real Numbers walks through how the number financed differs from the sticker price. And a personal loan can sometimes be split into a biweekly repayment schedule the way Mortgage Payoff Calculator: A Biweekly Payment How-To describes for a mortgage, though few banks offer it without you asking first.
$12,000 cash received, 12.44% interest rate, 36 months
| Correct: $12,765.96 gross principal | Mistake: $12,000 entered | |
|---|---|---|
| Monthly payment | $426.70 | $401.10 |
| Total interest | $2,595.25 | $2,439.54 |
| Gap from the real payment | $0.00 | $25.60 a month understated |
Illustrative standard amortization calculation with a 6% fee withheld from gross principal. The 12.44% annual interest rate excludes that fee and is not an APR quote or current offer. The comparison changes only the principal entered; lender disclosures and fee treatment may differ.
Worked example · illustrative numbers
Example: a rate typed in the wrong place
On the same $12,000 loan at a 12.44% annual interest rate excluding fees over 36 months, the correct payment is $401.10. Enter that 12.44% as though it were already a monthly rate, a mistake that's easy to make if a spreadsheet or a different calculator elsewhere expected a monthly figure, and the result jumps to $1,515.05.
The formula stayed the same in both runs. What changed is what that 12.44% figure was standing in for: an annual rate spread across 12 months, or a monthly rate on its own. Reading the label next to the input field before you type in a number catches this every time.
Put this into practice with Debtless
For a principal-and-interest estimate, use the loan principal and annual interest rate excluding fees, then compare fees and APR separately in the lender’s disclosures. Debtless can help organize a repayment plan; an estimate does not replace the loan agreement or establish affordability.
Common questions
Which loan amount should I enter in a payment calculator?
One input mistake is using cash received when the calculator needs the gross loan principal. If an origination fee is withheld from the advance, those amounts differ. The disclosure’s “amount financed” subtracts prepaid finance charges, so verify which figure the calculator requests rather than treating the terms as interchangeable.
Why did my calculator show a payment nearly four times higher than expected?
Check whether an annual interest rate was treated as a monthly rate. In this example, 12.44% per month produces $1,515.05 rather than the $401.10 payment calculated using 12.44% per year on $12,000 over 36 months.
Does every personal loan charge an origination fee?
No. Check the loan agreement for any fee and whether it is withheld, paid separately or already included in the principal. Do not add it twice or assume a disclosed “amount financed” figure is the gross principal.
Will a bank loan payment calculator account for a rate that changes later?
Not on its own. A calculator run once with today's rate assumes that rate holds for the full term. If your loan has a variable APR, rerun the calculator whenever the rate resets to see the new payment.
Sources & further reading
- CFPB: Do personal installment loans have fees?
- CFPB: Fixed APR vs. variable APR
- Bankrate: Average Personal Loan Interest Rates
- CFPB Regulation Z: Amount financed and prepaid finance charges
General education for U.S. readers, not individualized financial, legal or tax advice. Examples are hypothetical; lender terms and actual interest calculations can differ. Check your current statements and agreements.
Published by Debtless with AI-assisted drafting. How this journal is made · Suggest a correction