Debtless
What does a Bankrate-style auto loan calculator show?
A Bankrate-style auto loan calculator turns the amount financed, APR and term into an estimated monthly payment and total interest. Its amortization schedule shows when the final modeled payment lands—the payoff date for that one loan. A payoff plan answers a different question by ordering multiple existing debts for one monthly budget.
Use the Debtless auto loan payment calculator to run the payment formula with your own amount, APR and term before comparing that estimate with a full payoff plan.
| Feature | Bankrate auto loan calculator | Debtless payoff calculator |
|---|---|---|
| Inputs | Amount borrowed, loan term, new or used vehicle, interest rate | Current balance, APR, minimum payment, monthly extra payment |
| Monthly-payment output | Estimates the payment on a prospective auto loan | Uses the minimum payment you enter; does not price a new loan |
| Total-interest output | Shows total interest for the modeled auto loan | Shows estimated interest for each payoff method |
| Amortization schedule | Shows projected payment dates, principal, interest and remaining balance | Shows a month-by-month payoff schedule with the target debt, payment, interest, and remaining balance. |
| Extra-payment modeling | Not in this auto loan calculator; Bankrate offers a separate early-payoff calculator | Compares a recurring monthly extra payment across payoff methods |
| Multiple-debt planning | Models one auto loan | Compares the car loan with every entered debt |
| Best use | Estimate a prospective car loan before signing | Plan how to pay existing debts after signing |
What an auto payment calculator like Bankrate's actually computes
These calculators all run the same standard loan amortization formula: the monthly payment equals the amount financed times the monthly interest rate, divided by 1 minus (1 plus the monthly rate) raised to the negative number of payments. Enter the amount you're financing, the APR, and the term, and it solves for the fixed monthly payment on a fully amortizing loan.
That's genuinely useful before you sign anything, since it lets you compare a 60-month term against a 72-month term, or a 6% offer against a 9% one, without doing the algebra by hand.
What the number leaves out once you own the loan
The calculator's output is a projection for one prospective auto loan. Its amortization schedule shows where each modeled payment goes, but it does not track the actual balance as you make payments or place that loan beside the other debts competing for the same monthly budget.
Bankrate's auto loan calculator also has no extra-payment field. Bankrate offers a separate auto loan early-payoff calculator for that job, while Debtless starts after signing and compares one recurring monthly extra amount across the debts you already owe.
Turning a payment estimate into an actual payoff plan
A payment calculator answers one question: can I afford this payment. A payoff plan answers a different one: how do I get out of this loan, and everything else I owe, on purpose.
- Run the calculator with your real loan amount, rate and term to confirm the payment matches your offer.
- List every other debt you carry, not just the car loan, with its balance, APR and minimum payment.
- Decide an order to pay them down in; extra payments on an auto loan only shorten it if they're applied to principal, which is worth confirming with your lender.
- Use a tool that recalculates as balances change, instead of re-running a one-time estimate every month.
Why the loan term the calculator assumes matters more than it looks
Average loan terms have stretched out: 69.5 months for new cars and 67.9 months for used cars in the second quarter of 2026, according to Experian. A calculator will happily solve for a lower monthly payment at 75 or 84 months, but a longer term means more total interest paid on the same amount borrowed, even at the same rate.
This is also where how lenders apply payments becomes relevant: fees and interest are typically satisfied before principal, so stretching the schedule for a lower monthly number extends the stretch where you're paying mostly interest.
New car loans vs. used car loans, Q2 2026
| New car | Used car | |
|---|---|---|
| Average monthly payment | $765 | $542 |
| Average APR | 6.35% | 11.19% |
| Average loan term | 69.5 months | 67.9 months |
Figures from Experian's State of the Automotive Finance Market report, Q2 2026.
Worked example · illustrative numbers
Example: the payment a calculator shows vs. the plan behind it
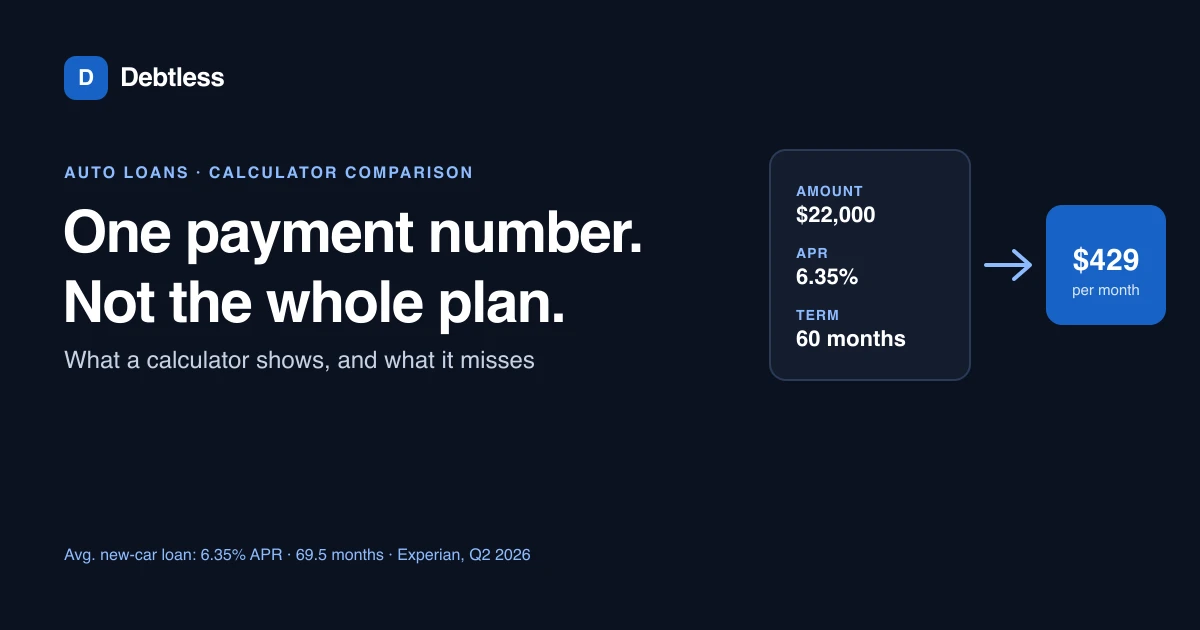
Say a calculator shows $22,000 financed at 6.35% APR over 60 months comes to about $429 a month, using the standard amortization formula. That's the number Bankrate's calculator, Debtless's calculator, or any other version of the same formula would return, since they all solve the same equation.
What the calculator doesn't show: after 12 months of $429 payments, about $5,147 total, only around $3,861 of that reduced the balance. The other roughly $1,286 covered interest, leaving about $18,139 still owed on the original $22,000. An extra $50 a month applied to principal from the start would cut both the payoff time and the total interest paid, which is the comparison a static calculator can't make on its own.
Put this into practice with Debtless
Debtless doesn't originate loans or estimate a payment before you sign; a calculator like Bankrate's or a lender's own tool is the right stop for that. Once you have the loan, enter its balance, APR and minimum payment into Debtless alongside your other debts, and the free iPhone app's payoff calculator shows how extra payments and payoff order change your debt-free date.
Common questions
Is a Bankrate-style calculator accurate for estimating my car payment?
Yes, for the number it's built to produce: a fixed monthly payment from a loan amount, an APR and a term, using standard amortization math. Any calculator using the same three inputs and the same formula returns the same payment.
Why did my estimated payment differ from my actual offer?
Usually taxes, fees, or an add-on like an extended warranty were rolled into the amount financed, or the APR on the offer differs from the rate you entered. Check the truth-in-lending disclosure on the actual offer against the numbers you typed in.
Does paying extra on an auto loan actually save money?
It can, if the extra amount is applied to principal rather than to future payments. Extra payments on an auto loan covers how to confirm that with your lender before you rely on it.
Can Debtless calculate my car payment the way Bankrate does?
Debtless's payoff calculator is built for a different question: once you know your balance, APR and minimum payment, it compares snowball, avalanche and cash-flow order across everything you owe, car loan included, rather than solving for a single new loan's payment.
Sources & further reading
General education for U.S. readers, not individualized financial, legal or tax advice. Examples are hypothetical; lender terms and actual interest calculations can differ. Check your current statements and agreements.
Published by Debtless with AI-assisted drafting. How this journal is made · Suggest a correction