Debtless
The short answer
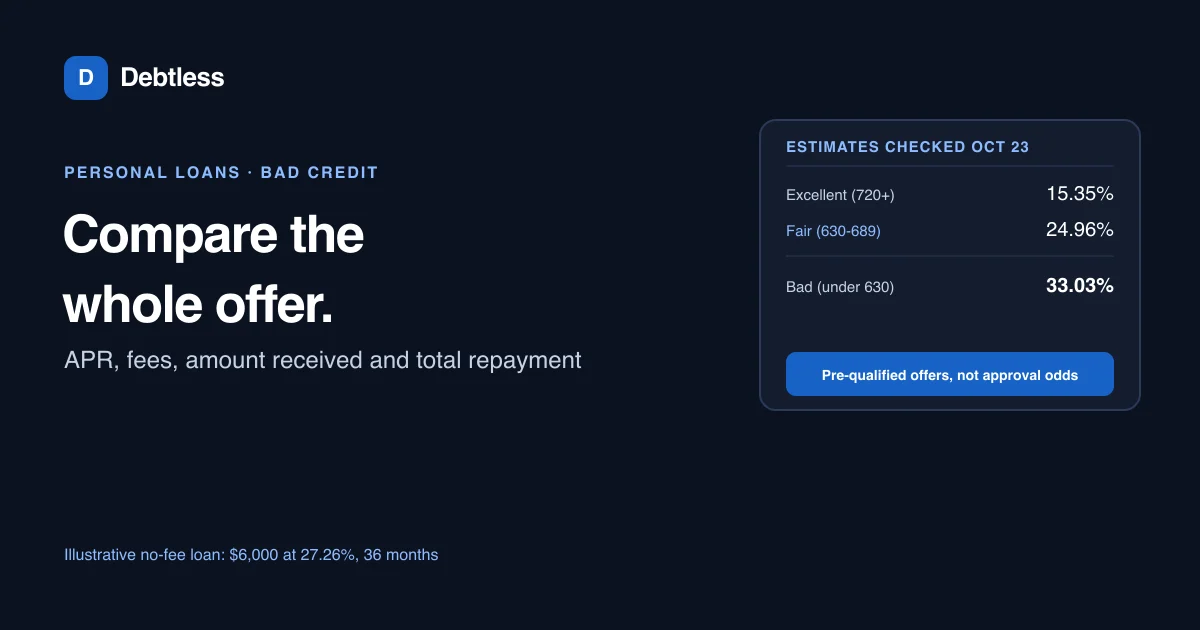
A bad-credit loan is a personal loan priced for higher credit risk. Checked October 23, 2026, NerdWallet's preceding-30-day pre-qualified offer data estimates 33.03% APR for scores below 630 and 15.35% for excellent credit. These estimates cover users who pre-qualified through NerdWallet, not all borrowers or the chance of approval. Compare an actual offer's APR, fees, monthly payment and total repayment with your available alternatives.
What rate can you actually expect with bad credit?
NerdWallet's estimates checked October 23, 2026 are 15.35% APR for scores of 720 and up, 19.72% for 690 to 719, 24.96% for 630 to 689, and 33.03% for 300 to 629. The source uses aggregate, anonymized offer data from users who pre-qualified through NerdWallet in the preceding 30 days; individual offers vary, and pre-qualification is not a binding approval.
A credit-tier average is a comparison point, not proof that a particular quote is affordable or competitive. NerdWallet notes that approval is harder below 630. Compare the APR, origination fee, amount you actually receive, repayment term and total payments on offers available to you before deciding whether a loan improves your existing payoff plan.
Is a balance transfer cheaper than a bad-credit loan?
A balance transfer card swaps the interest problem for a fee and a deadline instead. Transfer fees typically run 3% to 5% of the amount moved, and the 0% introductory period on the best cards usually runs 15 to 21 months, after which the remaining balance reverts to the card's regular APR.
The math favors the transfer only if the balance gets paid off inside that window; a debt consolidation loan spreads the same payoff over a longer, fixed term instead, which matters if the monthly payment a short transfer window demands doesn't fit the budget.
Does settling the debt hurt your credit more than borrowing does?
Settling for less than you owe is its own path, and it's a rougher one on a credit report than taking out a new loan. InCharge Debt Solutions, a nonprofit credit counseling agency, puts the typical hit at around 100 points, with the settled account staying on the report for seven years.
A new personal loan causes a smaller, shorter dip from the credit inquiry and the new account, then helps the score as it reports on-time payments. What a Lower Credit Card APR Actually Saves You covers the math on how much a lower rate is worth, which is worth keeping in view while deciding whether a new loan justifies the credit check.
What if you just pay down the cards you already have?
Paying off multiple cards at once doesn't require a new loan or account at all, just an order to attack them in. The debt avalanche method pays the highest-rate balance first to minimize total interest, while the debt snowball method clears the smallest balance first for faster wins; Debt snowball vs. avalanche: which debt goes first? compares both with a worked example.
That route skips the credit check, the origination fee and the new account entirely, a real advantage if a bad-credit score is itself the reason a loan or transfer card isn't approved at a workable rate in the first place. It also leaves the door open to revisit a loan or transfer later, once a few months of on-time payments have moved the score into a cheaper tier.
NerdWallet pre-qualified offer estimates, checked October 23, 2026
| Credit tier | Score range | Estimated APR |
|---|---|---|
| Excellent | 720-850 | 15.35% |
| Good | 690-719 | 19.72% |
| Fair | 630-689 | 24.96% |
| Bad | 300-629 | 33.03% |
Aggregate, anonymized offers from NerdWallet users who pre-qualified in the preceding 30 days, checked October 23, 2026. Estimates are not specific to a lender and do not measure approval chances.
Worked example · illustrative numbers
Example: $6,000 two ways with a 610 credit score
For a fictional comparison, assume $6,000 across two store cards and a personal loan with a 27.26% annual interest rate, no origination fee or other charges, and 36 equal monthly payments. With no fee, the modeled APR equals the interest rate: the modeled payment is about $245.79 a month and total interest is about $2,848.40, before any payment-rounding adjustment. The 27.26% is an illustrative input, not the current NerdWallet estimate or an offer available to someone with a 610 score.
If approved for a transfer with sufficient available credit, the same $6,000 moved to a balance transfer card with a 3% fee and an 18-month 0% intro period results in a $6,180 balance to repay and requires about $343.33 a month, with final-payment rounding adjusted, to clear it inside the promo window, with no interest at all if it's paid off on time, just the $180 fee. The transfer wins on cost here, but only because the higher monthly payment is realistic; stretched past 18 months, the remaining balance starts accruing the card's regular APR instead, which can erase the savings fast on whatever is still outstanding.
Put this into practice with Debtless
Debtless compares avalanche, snowball and a custom order side by side on your actual balances and rates, so you can see whether a new loan, a transfer, or just reordering your current cards gets you debt-free sooner, inside the free iPhone app's payoff calculator.
Common questions
Can you get a personal loan with a credit score under 600?
Eligibility depends on the lender; a credit score alone does not establish it. NerdWallet reports that approval is harder below 630. Its 33.03% estimate covers recent pre-qualified offers, not the percentage of applicants approved or a guaranteed rate.
Is a balance transfer always better than a bad-credit personal loan?
Only if the balance gets paid off before the 0% intro period ends, typically 15 to 21 months. Past that window, the card's regular APR applies to whatever's left, which can cost more than the loan would have.
Does debt settlement hurt your credit score more than taking out a loan?
Generally yes. A settled account can cost around 100 points and stays on a credit report for seven years, according to InCharge Debt Solutions, while a new loan causes a smaller, shorter dip that recovers as it reports on-time payments.
What's the cheapest way to pay off multiple credit cards?
If a lower-rate loan or transfer card isn't available, the debt avalanche method, paying the highest-APR balance first, minimizes total interest without opening any new account at all.
Sources & further reading
- NerdWallet: Average Personal Loan Interest Rates
- Bankrate: Best Bad Credit Loans
- Experian: How to Avoid Balance Transfer Credit Card Fees
- InCharge Debt Solutions: Debt Settlement vs. Credit Score
General education for U.S. readers, not individualized financial, legal or tax advice. Examples are hypothetical; lender terms and actual interest calculations can differ. Check your current statements and agreements.
Published by Debtless with AI-assisted drafting. How this journal is made · Suggest a correction